Wimbledon buy to let: a practical guide for landlords
Wimbledon buy to let appeals to investors who want a London location with more than a single reason for tenants to stay. Transport connections, local shops, parks, cultural venues and a choice of neighbourhoods all contribute to its appeal. Yet an attractive place to live is not automatically a profitable property investment. The purchase price, realistic rent, running costs and financing must work together.
The most useful question is therefore not simply whether Wimbledon is a good rental location. It is which property suits your budget, intended tenants and responsibilities as a landlord. This guide considers the local opportunity alongside the practical checks that matter in October 2026. It is general information, not personalised investment, mortgage, legal or tax advice; income and capital growth are not guaranteed.
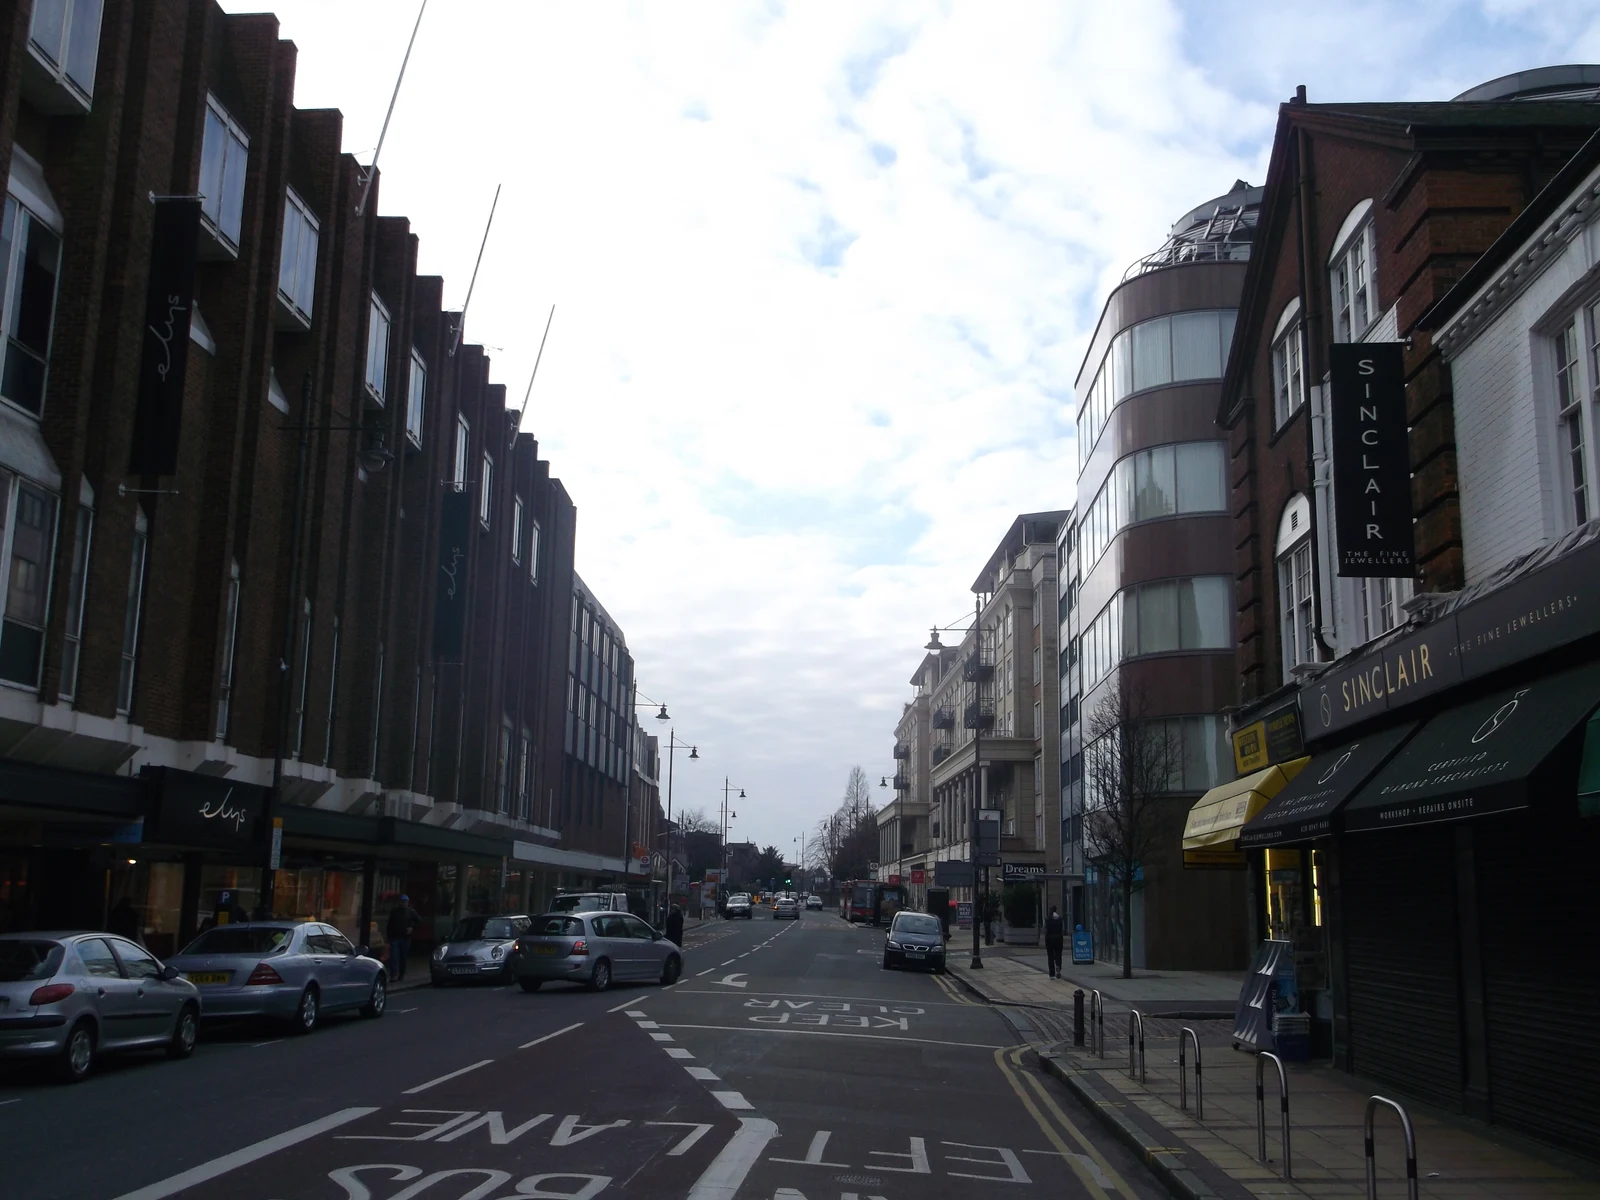
Hero photograph: Worple Road, Wimbledon, January 2013, by David Anstiss, CC BY-SA 2.0. An archive streetscape, not a current property listing. Photograph credits and licences.
Why consider Wimbledon for buy to let?
Wimbledon's attraction rests on everyday usefulness as much as its international tennis reputation. A tenant can choose between the town centre's services, the Village's distinctive high street, quieter residential streets and access to substantial green space. For landlords, that variety creates several possible letting propositions rather than one uniform market.
A well-presented flat near transport may appeal to commuters, while a practical house with storage and outdoor space may suit a household looking for a longer-term home. These are potential audiences, not evidence that every property will let quickly. Ask for recent comparable lettings, the achieved rent and the time required to find a tenant, rather than relying on optimistic advertised figures.
For a wider view of the location's strengths and compromises, read our guide to buying property in Wimbledon. Investment decisions should begin with the same careful assessment of condition, access and long-term suitability as an owner-occupier purchase.
What official rental figures tell us
The Office for National Statistics' Merton housing page, updated on 15 September 2026, recorded an average private rent of £2,172 a month in August 2026. That was 5.4% higher than August 2025. The corresponding annual rise across London was 3.5%. This provides a positive indication of rental growth in the wider borough, without proving that every Wimbledon landlord experienced that increase.
The same release reported Merton averages of £1,639 for one-bedroom properties and £2,024 for two-bedroom properties. Its provisional average house price was £616,000 in July 2026. These are borough-wide statistics covering different property mixes and periods, not a quotation for a particular SW19 or SW20 home.
Use the ONS housing and rental statistics for Merton as background, then obtain a property-specific appraisal. Do not divide the average rent by the average house price and describe the result as an achievable Wimbledon yield: the underlying homes are not a matched investment sample.
Choose the neighbourhood around the letting proposition
Near Wimbledon town centre, investigate properties whose appeal includes convenient access to the station, shopping and other services. A shorter journey can be valuable, but visit the actual street to assess traffic, evening activity and noise. A map distance does not capture the experience of walking home.
South Wimbledon offers a different transport proposition around the Northern line. Wimbledon Park has its own District line station, while Wimbledon Chase and Raynes Park provide further options for different working patterns. Compare the route your likely tenants would actually use, including changes, station access and weekend services.
The Village and Common-side locations may appeal to people prioritising atmosphere and outdoor life. Higher acquisition costs can nevertheless make the income calculation harder. Our comparison of the best areas to live in Wimbledon helps explain these lifestyle differences; it is not a league table of investment returns.
Flats and houses: compare the whole ownership cost
A flat may require less initial capital than a larger house, but leasehold costs can materially affect the result. Check the remaining lease term, service-charge accounts, reserve fund, planned major works and any restrictions on subletting. Ask your solicitor to explain the lease, not merely confirm that one exists.
For a house, investigate the roof, drainage, heating, windows and external maintenance. A garden can strengthen the letting proposition while also creating upkeep responsibilities. Neither property type is inherently the better investment: the decision depends on the price, likely tenant experience and costs over the period you expect to own it.
Calculate gross yield, then look beyond it
Gross rental yield is annual rent divided by purchase price, multiplied by 100. For a purely hypothetical purchase at £500,000 with rent of £2,400 a month, annual rent would be £28,800 and gross yield 5.76%. These assumptions are illustrative, not a Wimbledon valuation, advertised opportunity or forecast.
Suppose annual allowances were £3,000 for service charges, £1,500 for repairs, £2,400 for management including VAT, £600 for insurance and £1,200 for lost rent during vacancies. That totals £8,700, leaving £20,100 before mortgage costs and tax. The resulting operating return on purchase price would be 4.02%, before acquisition costs and other potential expenses.
A hypothetical £300,000 interest-only loan costing 5% annually would then require £15,000 in interest, leaving £5,100 before tax. This is not a lending quote. Higher charges, a major repair or a longer vacancy could reduce that amount substantially. Include legal fees, stamp duty and initial works when assessing the return on all the money committed.
Budget for purchase taxes and finance
Stamp Duty Land Tax can be a substantial part of the acquisition budget. HMRC's residential guidance states that buyers usually pay an extra five percentage points where the purchase means they will own more than one residential property. Additional rules can apply to non-UK residents, companies and particular transactions.
Do not assume that calling a purchase “buy to let” determines the tax bill. Ask a solicitor or tax adviser to confirm the treatment for your circumstances before making an offer. Mortgage deposits, arrangement fees, lender stress tests and acceptable property types also vary; obtain independent advice rather than treating a generic online example as approval.
Understand the tenancy rules operating in 2026
The government's landlord overview confirms that major Renters' Rights Act changes took effect in England on 1 May 2026. For the assured private tenancies covered by the reforms, assured periodic tenancies replaced the previous assured shorthold model. An investment plan should not depend on a routine fixed-term expiry delivering vacant possession.
The overview also explains the end of section 21 no-fault eviction and the need to use lawful possession grounds and the correct procedure. Selling or moving into a property does not mean immediate recovery: restrictions and notice requirements apply. Take advice on existing tenancies and any transitional position before buying with tenants already in place.
Landlords must publish an asking rent when advertising and cannot encourage or accept offers above it. Rent increases follow the section 13 process, with at least two months' notice and no more than one increase a year. These rules make accurate initial pricing and organised management especially important.
Check licensing against the exact address
Merton Council distinguishes mandatory HMO licensing, additional HMO licensing and selective licensing. Its published overview says mandatory licensing may apply where an HMO accommodates five or more people forming more than one household. Other schemes depend on occupancy and the property's ward.
The council lists additional licensing for certain three- or four-person HMOs in seven named wards, and selective licensing for single-household properties in four named wards. It does not describe these as blanket schemes covering every Wimbledon rental. Check the current address-level position with the council, including exemptions, and do not assume a postal description establishes the ward.
Planning permission is a separate question from licensing. If considering an HMO, verify the lawful use, any Article 4 restrictions, room standards and lender and insurer requirements before agreeing a price based on several separate rents.
Buy a home that can be managed responsibly
Before exchange, establish what work is needed for a safe, comfortable letting. Commission appropriate surveys and obtain advice on gas and electrical safety, alarms, energy performance, deposit protection and required tenant information. Check the rules applying at the tenancy's start rather than relying on paperwork from a previous owner.
Practical improvements often matter more than decorative extras. Effective ventilation, reliable heating, usable storage and durable finishes can improve the tenant experience and reduce recurring problems. Ask for realistic repair quotations and maintain a reserve; a landlord must still respond to problems when the monthly cash flow is disappointing.
Treat tennis-season income as a separate business case
The Championships make Wimbledon internationally recognisable, but short seasonal accommodation is different from a normal long-term letting. Do not combine a full year's residential rent with a premium tournament letting in the same forecast as though both can occupy the property at once.
Short lets require separate checks covering planning, London rules, mortgage and lease permissions, insurance, management and the type of occupation agreement. Nor can a landlord simply interrupt an existing tenant's home for the tournament. For a straightforward buy-to-let assessment, begin with sustainable ordinary residential income and exclude speculative seasonal premiums.
Plan the tax position and eventual exit
Cash left after mortgage payments is not necessarily taxable profit. HMRC restricts residential finance-cost relief for individual landlords through a basic-rate tax reduction, subject to limits, rather than the old full deduction against rental income. Personal circumstances can therefore change the investment result materially.
Company ownership has different costs and tax implications and is not automatically preferable. Discuss income tax, potential capital gains, borrowing and ownership structure with a qualified adviser. Also consider how you would sell: a tenanted sale and a vacant sale involve different practical considerations, and neither an immediate buyer nor a higher future price is guaranteed.
A practical checklist before making an offer
Request a written rental appraisal that identifies the comparable homes used, their condition and whether the quoted rents were achieved or merely advertised. Ask what might prevent the property achieving the proposed rent. A useful appraisal should explain drawbacks as well as advantages, including awkward layouts, limited storage or a less convenient station walk.
Next, put the acquisition budget, recurring expenses and available cash reserve on one page. Run a second version with a lower rent, higher borrowing costs and an unexpected repair. If the purchase only works when every assumption is favourable, renegotiate the price or consider another property rather than relying on future growth to repair the calculation.
Finally, establish who will handle viewings, referencing, inventories, inspections and emergency repairs. Obtain a clear management quotation showing VAT and any separate charges. Good preparation gives both landlord and tenant a clearer start, while helping you decide whether this particular investment fits the time, money and responsibility you can commit.
Is Wimbledon buy to let right for you?
Wimbledon offers a credible setting for a carefully selected rental home: varied neighbourhoods, useful transport choices and amenities with year-round relevance. Official Merton figures provide encouraging rental context, but the strongest investment case is built from the exact property rather than the postcode's reputation.
Start with a realistic rent appraisal, independent finance advice, a full cost schedule and a clear compliance plan. Compare alternatives and stress-test a less favourable outcome before committing. To discuss a local search with estate agents Wimbledon, speak to The Wimbledon Estate Agent about finding a property that suits your objectives and budget.
Research checked 17 October 2026: ONS Merton release updated 15 September 2026; GOV.UK Renters' Rights Act landlord overview and residential SDLT guidance; HMRC finance-cost relief guidance; Merton Council property-licensing overview. Figures retain their stated reference periods and may be revised. Confirm current legal, licensing and tax requirements with the appropriate authority or adviser.
Share this article